

Ditch: Pay Off Debt Faster analysis by Appwee
Debt rarely feels difficult because the arithmetic is impossible. It feels difficult because the details are scattered: one balance sits in a banking app, another arrives by email, and the next payment date is easy to forget. I found Ditch: Pay Off Debt Faster most useful as a place to turn that scattered information into a plan I can actually look at and maintain. It is a free finance app from Ditch Technologies, Inc, designed around automating payoff planning and tracking debt rather than acting as a replacement for a bank.
My first impression was that its value depends less on constant daily use and more on setting up a clear starting picture. Once I know what I owe, what each payment requires, and how much room I have in my budget, a payoff tracker can make progress visible. That sounds simple, but visibility matters: a debt plan is much easier to follow when I do not have to reconstruct it from several unrelated accounts every time I want to make a decision.
From a messy debt list to a workable payoff routine
Starting with the financial situation I actually have
The right way to approach this app is not to open it expecting an instant answer. I would first gather the information needed to describe my current debts accurately. That means checking balances, minimum payments, interest details where available, and payment timing before entering anything. The app can help organize the plan, but it cannot make an incomplete or outdated list reliable.
This is one of the most important practical points. If I enter a balance from an old statement, forget a small account, or confuse a minimum payment with the amount I usually send, the resulting payoff picture may look reassuring while being wrong. I treat the first setup as a short financial inventory, not as a quick form to rush through.
Once the information is ready, the app’s purpose becomes clearer. Rather than making me stare at a total debt number, it gives me a framework for thinking about repayment as a sequence. That is especially helpful when several balances compete for attention. I can use the plan to decide what deserves focus and then return to the tracker to see whether my behavior is moving in the intended direction.
For someone who has only one balance and already has a dependable repayment routine, the benefit may be smaller. A basic note or spreadsheet could be enough. The stronger case for this app is a borrower who keeps postponing decisions because the overall situation feels too complicated to hold in their head.
The step-by-step flow I would use
I would begin by entering each debt separately instead of combining everything into one figure. Separate entries preserve the context that makes a repayment plan useful. A total tells me how large the problem is; individual debts help me understand what needs to happen next.
After that, I would review the planned payment approach before treating it as a commitment. The app’s automation angle is appealing because it encourages a repeatable system rather than relying on motivation every month. Still, I would compare any suggested or scheduled payoff behavior with my actual bank budget. A plan that looks efficient on paper can become stressful if it leaves too little cash for rent, food, utilities, or irregular expenses.
My preferred workflow would be to set the plan after payday, check upcoming obligations, and then record the payments I genuinely made. That creates a useful handoff between the app and my real financial life: the app provides structure, while my bank account and statements confirm what happened. I would not consider a debt marked as progressing merely because I intended to pay it.
One non-obvious advantage of this approach is that it separates planning from emotional decision-making. When I am tired or worried, I am more likely to avoid opening several creditor accounts. A single payoff view gives me a calmer place to review the next action. I can look at the plan during a scheduled weekly check-in instead of repeatedly thinking about debt without doing anything concrete.
I would also use the tracker to test affordability before increasing payments. For example, if I receive extra income, I would first ask whether using all of it for debt would create a new shortfall later. A safer workflow is to reserve money for known near-term costs, then apply a deliberate extra amount rather than making an impulsive payment that forces me to borrow again.
Where the handoffs matter most
The most important handoff is between the app and the information supplied by creditors. A tracker is only as current as the figures I maintain. Interest can change a balance, a payment can post later than expected, and a new purchase can undo progress on a revolving account. I would therefore treat the app as a planning dashboard, not as an unquestionable financial record.
The next handoff is between the payoff plan and my monthly budget. A debt strategy should fit the money that remains after essential expenses, not the other way around. I like the idea of having a dedicated place to track the target, but I would still keep a separate budget view for everyday spending. This app is focused on debt, so it should not be expected to explain every part of household cash flow.
There is also a handoff between intention and action. If I decide to make an additional payment, I need to complete that payment through the appropriate financial channel and then update my tracking. This sounds obvious, yet it is where many planning tools lose practical value. A beautifully organized plan cannot compensate for missed transfers or a payment sent to the wrong account.
For couples or families, the handoff can be more complicated. One person may maintain the plan while another controls the account used for payment. In that situation, I would agree on who checks balances, who confirms transactions, and when the plan is reviewed. Without that small piece of coordination, the app could become a private list that does not reflect the household’s shared decisions.
What the result feels like in everyday use
Imagine a typical month in which I have a credit card balance, a personal loan, and an unexpected medical bill. Before using a dedicated tracker, I might pay the minimums, make one extra payment when possible, and then lose track of whether the balance is falling as quickly as I hoped. With a structured payoff view, I can start the month by checking the plan, confirm what is affordable, make the payments, and return later to record the outcome.
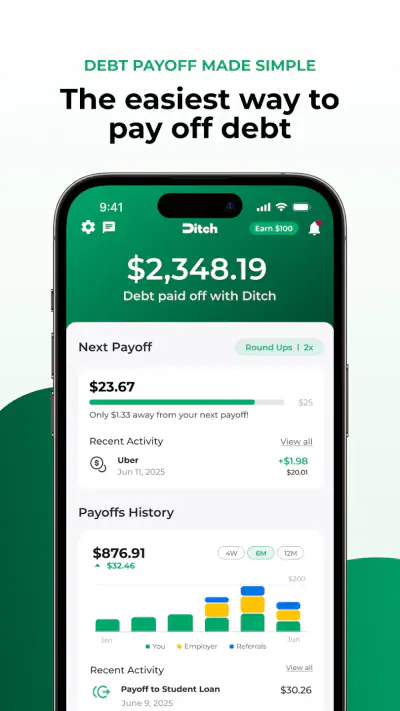
The result is not instant debt elimination. The result is a more visible chain of decisions. I can see which balance is receiving attention, whether my extra payment was actually made, and whether the remaining plan still fits my circumstances. That feedback is valuable because it replaces vague optimism with a routine I can repeat.
I also found that progress tracking can help with motivation in a more practical way than inspirational reminders. When the total changes slowly, it is easy to believe that payments are not accomplishing much. A record of completed actions gives me evidence that the routine is working, even when the finish line is still far away.
That said, I would avoid judging the app only by how satisfying the progress display feels. The real outcome depends on payment amounts, interest, new borrowing, and whether the entered information stays accurate. I see the app as a tool for making better decisions, not as a guarantee that a particular payoff date will remain unchanged.
Where the flow breaks down
The first weak point is setup discipline. People who want a completely automatic experience may be disappointed if they still need to verify balances and keep the plan updated. Automation can reduce repeated effort, but it does not remove the need for financial judgment. If I ignore statements or stop recording changes, the app’s picture can gradually drift away from reality.
The second limitation is scope. This is a debt-focused finance app, not a full replacement for a bank, a complete household budget, or professional financial advice. Someone who needs detailed investment tracking, tax planning, business accounting, or extensive bill management may be better served by a broader finance platform. Adding another app to that setup could create more maintenance instead of less.
I would also be cautious if my income changes sharply from month to month. A fixed payoff routine may be easy to follow with a regular salary, but freelancers, seasonal workers, and people managing irregular hours need to review the plan more often. In those cases, I would set a conservative baseline and treat extra payments as optional until the month’s income is secure.
Another trade-off concerns motivation. A tracker can make debt feel manageable, but it can also make the numbers harder to ignore. That is useful for accountability, though not everyone wants a dedicated reminder of financial stress on their phone. If opening the app increases anxiety without leading to action, a simpler monthly review with a trusted adviser or spreadsheet might be a better fit.
Who should use it and who should choose another approach
I would recommend it to someone with multiple debts who wants a focused payoff routine without building a system from scratch. It is also a good match for a person who understands their income and expenses but struggles to maintain momentum after the first few payments. The app’s narrow purpose can be a strength because it keeps attention on reducing balances rather than surrounding the task with unrelated financial features.
I would be more selective for someone who already has a detailed spreadsheet, automatic bank categorization, and a reliable review habit. In that case, switching tools may not add enough value unless the app’s payoff workflow feels substantially easier to maintain. The best system is the one I will update consistently, not necessarily the one with the most specialized presentation.
It may also be the wrong choice for anyone expecting the app to negotiate with creditors, lower interest rates, or decide what is financially safe without personal input. Those are different needs. A debt-management professional, creditor hardship program, or broader budgeting service may be more appropriate depending on the situation.
Practical questions I would answer before installing
One question is whether it costs anything to begin. The app is free to download, while in-app purchases range from around six dollars to around ninety dollars per item. I would check the purchase details carefully before committing to anything, especially if I only need basic tracking and want to keep my debt-reduction costs close to zero.
Another question is whether an older device can run it. The listed minimum is Android 8.0, so compatibility should be considered before installation. On iOS, I would still check the relevant store requirements for the particular device I plan to use. The current version is 1.5.6, which is useful context when deciding whether my phone’s software is reasonably up to date.
People often wonder whether a finance app is suitable for a shared household. I would use it as a planning aid, but I would not assume that it replaces an agreed process between partners. Decide who enters changes, who verifies payments, and how often the plan is reviewed. That makes the app part of a household routine instead of a second, disconnected record.
A final practical question is how often to open it. I would not check it obsessively. A short review after income arrives, another check after payments clear, and an occasional update when a balance or budget changes should be more useful than constant monitoring. The goal is to support consistent action, not turn debt into an all-day source of worry.
My overall view after following the workflow
Ditch: Pay Off Debt Faster earns its place as a focused finance tool because it turns repayment from a vague intention into a process with a starting point, planned actions, and visible follow-through. I like it most when I imagine using it alongside real statements and a realistic budget: enter the debts, choose an affordable routine, complete the payments through the proper channels, then update the record.
Its public reception is encouraging, with a 4.8 average from around 1.1 thousand ratings and more than 10 thousand installs. It is rated for Everyone, which makes the presentation broadly approachable, but an accessible interface does not remove the need for careful financial decisions. The developer, Ditch Technologies, Inc, has made a focused product rather than an all-purpose money manager, and that focus is both its clearest advantage and its main boundary.
I would recommend trying it if debt feels disorganized and you want a dedicated place to maintain a payoff plan. I would skip it if you need full banking automation, advanced budgeting, or professional debt intervention. For the right user, the payoff is not a promise of effortless results; it is the quieter benefit of knowing what to do next and having a record that shows whether I actually did it.
Gallery
Ditch: Pay Off Debt Faster Pros and Cons
- Clear payoff tracking helps you monitor progress toward becoming debt-free.
- Supports focused repayment planning instead of relying on rough estimates.
- Simple interface makes regular debt updates quick and manageable.
- Useful motivation as balances decrease and payoff milestones become visible.
- Can help organize multiple debts in one convenient place.
- Requires accurate balance and interest details for useful repayment projections.
- Manual updates may become tedious when account balances change frequently.
- May not connect directly to every lender or financial institution.
- Debt payoff tools cannot replace personalized financial advice.
- Some features or planning options may require a paid subscription.
Ditch: Pay Off Debt Faster Frequently Asked Questions
What is Ditch: Pay Off Debt Faster, and how does it work?
Ditch is a debt-management app designed to help you understand your borrowing, organize repayment goals, and make progress toward becoming debt-free. After entering or connecting information about your debts, the app can help present balances, interest rates, and payment details in one place. It is primarily a planning and tracking tool, so it does not automatically eliminate debt or replace professional financial advice.
Can Ditch connect to my bank or credit accounts safely?
Depending on your location and the version of the app available, Ditch may offer account connections through a third-party financial-data provider. Before linking an account, review the permissions requested, privacy policy, and security information carefully. You should also use a strong password and enable any available security features. If you prefer not to connect accounts, check whether the app supports manual debt entry and updates.
Does Ditch make payments to creditors automatically?
Ditch should not be treated as a replacement for your lender, bank, or bill-payment service. Its main purpose is to help you organize debt and follow a repayment strategy, while payment features may vary by region and app version. Always confirm whether a payment has actually been scheduled or processed with the creditor, and continue making required payments on time to avoid fees or damage to your credit.
Is Ditch free to download, or does it require a subscription?
The app may be free to download while offering optional premium features, subscriptions, or in-app purchases. Pricing, trial periods, and available tools can change, so check the current listing in the Google Play Store or Apple App Store before installing. If you begin a trial, read the renewal terms carefully and cancel through your device’s subscription settings if you decide not to continue.
Is Ditch suitable for everyone trying to pay off debt?
Ditch can be useful for people who want a clearer overview of their balances, repayment progress, and financial habits, particularly when managing several debts. However, it may not be enough for users facing severe financial hardship, collections, legal action, or complex tax and credit issues. In those situations, consider speaking with a nonprofit credit counselor or qualified financial professional before making major repayment decisions.














